

Oct '25 •
Paypal vs Sofi
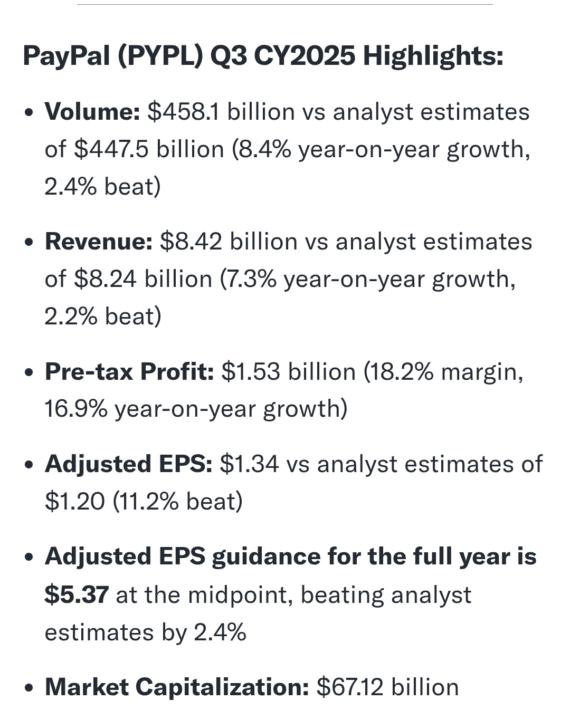
From @StockStory: Amazing Q3 performance! Are you buying their growth story?

6d •
Zoetis (ZTS)
I think it deserves a thread. - "Zoetis Inc. has fallen 71% from its 2021 peak, now trading at 2017 levels, as pricing power eroded and pet medicine volumes declined. - Despite near-term headwinds, Zoetis maintains industry-leading margins and is positioned to weather price wars better than rivals due to its product mix and scale. - Patent expiries for Apoquel and Simparica in 2030/2032 are key risks, but a robust pipeline of 12 candidates could offset revenue losses if half succeed."

🍀
5d •
October 9 2026 VIP Coaching Call
- S&P 500 and QQQ update (Bearish) - Monthly income: Google Oct 9 Expired with full profit - Long term portfolio - Exited MSFU for 45% gain in 6-8 months - Buy hedge in case market goes down - Increase cash to 10% - Analysis on VRT - AI data centre - Analysis on ISRG - Medical devices Watch the latest coaching call (VIP plan): https://www.skool.com/invest-retire-community-1699/classroom/8932256b If you don't have VIP access yet, you can get it here: https://www.skool.com/invest-retire-community-1699/plans Cheers, Eric Eric Seto, CPA, CIM ex-KPMG Auditor and Lecturer Founder of 5MinInvesting.com

🍀
18d •
September 25 2026 Coaching Call
- S&P 500 and QQQ update (Bearish next week) - Oil price update - Analyze the latest monthly income trade MA - Long term portfolio - Analyzing existing positions - Reduce cash from 10% to 2.5% and buy hedge as insurance - Analysis on SOFI Watch the latest coaching call: Watch the coaching call on skool https://www.skool.com/invest-retire-community-1699/classroom/8932256b Required Skool VIP access (If you don't have VIP access, get it here: https://www.skool.com/invest-retire-community-1699/plans) For students of Investing Accelerator, please go to the student only community Cheers Eric Eric Seto, CPA, CIM

1-30 of 470

skool.com/invest-retire-community-1699
Investment & Retirement Strategies for busy full-time professionals. Get your free invite here: https://5mininvesting.com/free-case-study/
Leaderboard (30-day)
1

+856
2
🔥
+735
3
+538
4

+480
5

+410
Powered by